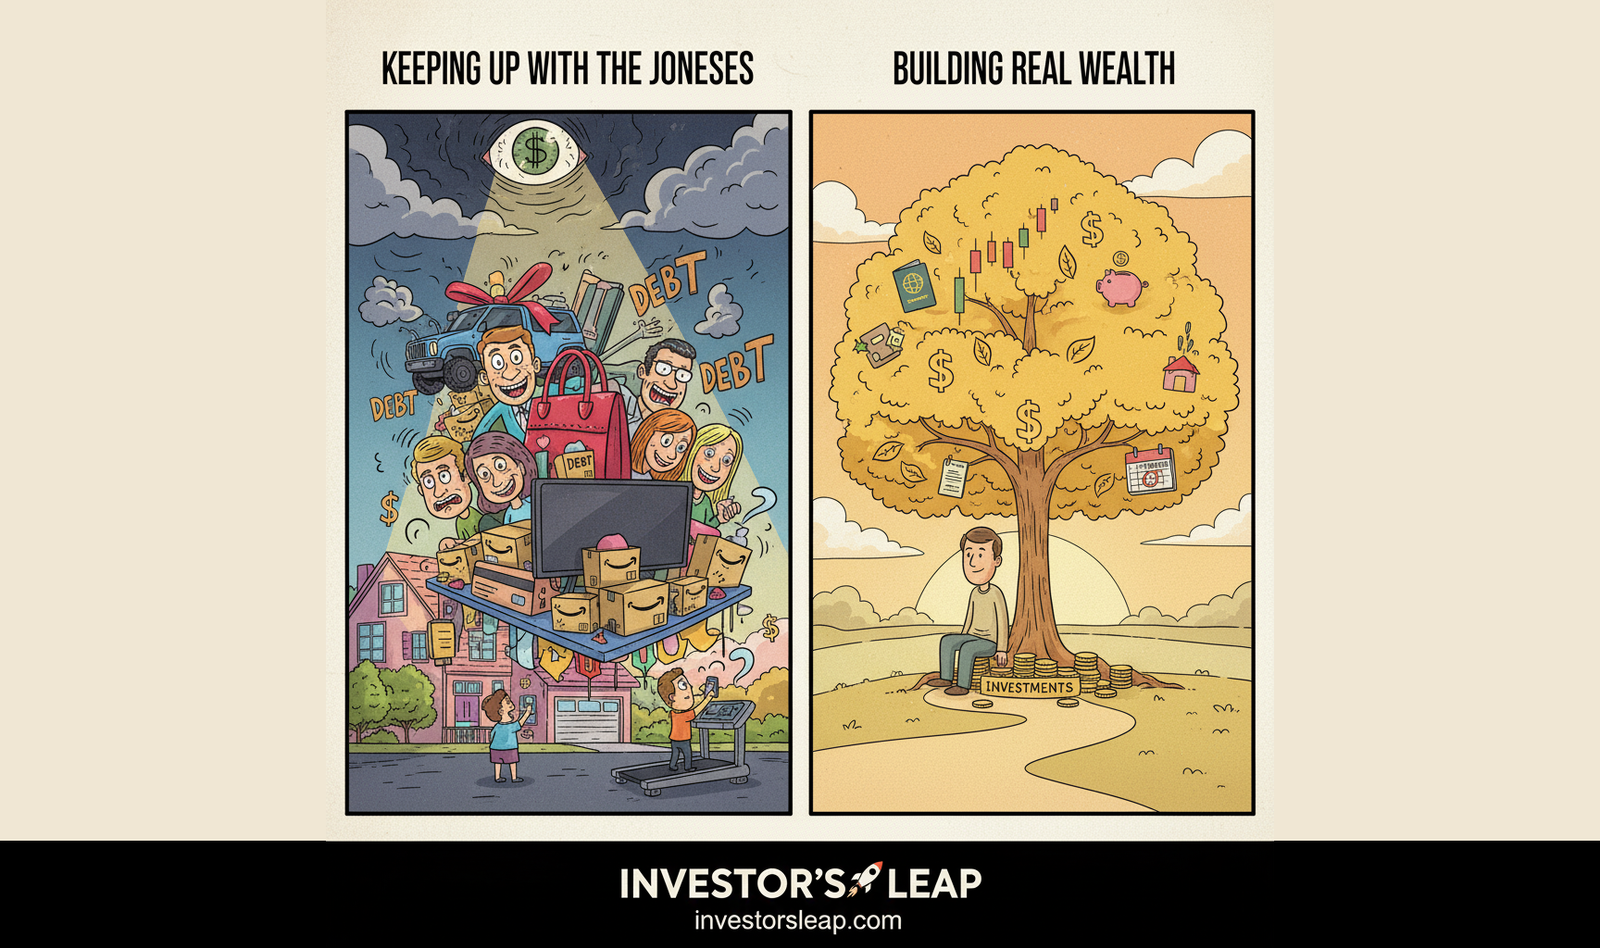
It’s the silent killer of budgets, the source of unnecessary debt, and the biggest thief of financial peace: The Comparison Trap, better known as “keeping up with the Joneses.”
In the age of social media, the Joneses are no longer just your neighbors. They are the curated feeds of your friends, the influencers with perfect kitchens, and the colleagues driving luxury cars. This relentless social pressure creates a phenomenon called lifestyle creep, where your spending automatically rises to match or exceed the perceived success of others, regardless of your actual needs or financial plan.
The hard truth? Trying to look wealthy often ensures you never actually become wealthy.
Ready to break free from the trap, silence the noise, and start building true wealth? Here is your guide.
The Illusion of Affluence: Why The Joneses Aren’t a Benchmark
The first step to stopping the comparison trap is understanding the illusion.
1. You See the Purchase, Not the Debt
A purchase shows what someone bought, not their income, debts, savings, or priorities. They may have planned carefully or borrowed; you cannot tell from a photo. Compare the purchase with your own obligations.
2. Everyone Has Their Own “Joneses”
Comparison can keep moving the target. Define a goal you can measure yourself, such as an emergency cushion or a sustainable monthly debt payment.
3. Lifestyle Creep Is Silent
Lifestyle creep is the subtle process where increases in income lead to increases in spending on unnecessary items. You get a raise, and suddenly you “need” a higher cable package, more expensive takeout, or a bigger apartment. If your savings rate never increases alongside your income, you are simply spending more money to stay in the same financial place.
3 Strategies to Escape the Comparison Trap
Breaking the comparison habit requires intentional mental and financial shifts.
1. Redefine “Success” on Your Own Terms
You need a personal financial north star that is completely independent of external influence.
- Financial Goal Focus: True success is not a car or a house; it’s financial independence—the ability to choose how you spend your time. Write down exactly what that means to you (e.g., I will be financially independent by age 55).
- Create Your Wealth Statement: Change your internal dialogue from “I wish I could afford that” to “That purchase does not align with my goal of becoming financially free.”
2. Create Friction and Accountability
Make it harder to make impulse purchases driven by social pressure.
- The 72-Hour Rule: If you feel the urge to buy something expensive because someone else has it, impose a mandatory 72-hour waiting period. Often, the desire fades when the social pressure cools.
- Financial Visibility: Make your spending public (to your partner) or brutally honest (to yourself). Track every dollar. When you see exactly how much that “keeping up” purchase takes away from your savings goal, the temptation loses its power.
3. Change Your Inputs
Social media is the comparison trap accelerator. You must manage what you consume.
- Curate Your Feed: Mute or unfollow accounts that primarily showcase extravagant, aspirational lifestyles that trigger comparison spending.
- Follow Inspiring Wealth Builders: Replace those feeds with content from people who prioritize financial literacy, intentional saving, and long-term investment. They offer inspiration for building wealth, not displaying it.
🚀 Investor’s Leap: The Wealth-Building Gap
Measure your own progress over time: bills covered, expensive debt reduced, and saving you can maintain. Other people’s purchases do not determine your next financial step.
Estimate your wealth-building gap from purchases you actually planned but skip. Forgoing $150 of clothing and a $50 upgrade creates a potential $200 gap, not automatic savings. Check upcoming bills, then decide whether available cash belongs in a buffer, debt repayment, or a long-term investment. Investment returns are uncertain.
Choose a goal because it matters to you, then make one affordable decision toward it. Enjoying purchases and building savings can coexist. The aim is a sustainable plan, not judging other people’s choices.
What is one item you will consciously not buy this week to stop chasing the Joneses?
Next step: Turn that decision into progress with Saving 101, then set a concrete long-term target with the Million-Dollar Goal Calculator.
Try a seven-day comparison reset
Declining a $180 upgrade with a $12 monthly charge avoids $180 upfront and $144 over the next year under those assumptions. The future $144 is not cash available today. Log comparison triggers for seven days, review whether each purchase serves your own goals, and transfer only affordable money actually retained.
Source: Official guidance from CFPB.